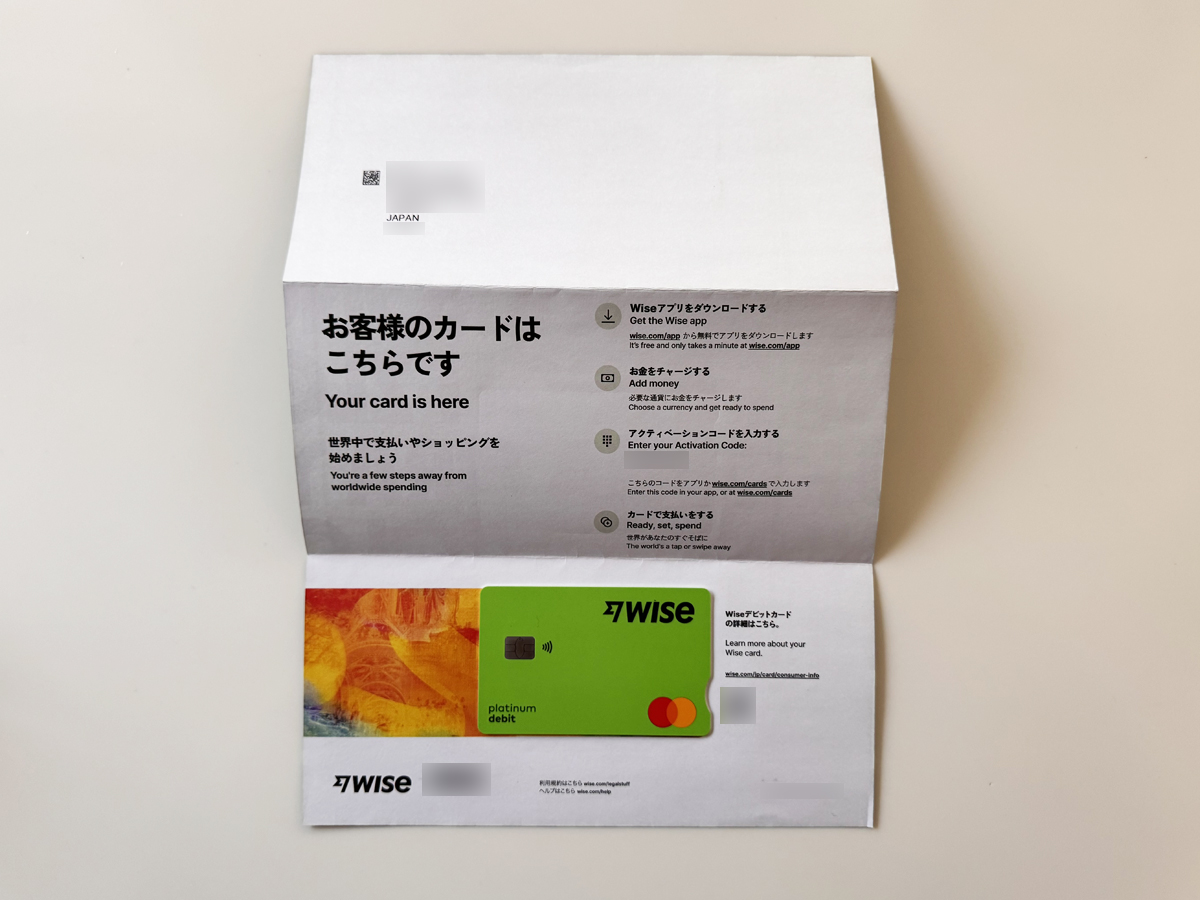

Short answer: yes — the Wise card works well in Japan as a spend-and-FX layer, but it is not a full Japanese bank account. It shines when you earn in USD, EUR, or GBP and spend in yen: transparent conversion, a multi-currency balance, and a Visa/Mastercard debit card accepted by most card-taking merchants. Pair it with an IC card for transit and some cash for the shops and clinics that still refuse plastic.
Does Wise work in Japan? Quick answer
Great for: converting foreign income to yen, card and tap-to-pay at chains, hotels and online, and holding a yen balance you can spend on demand.
Not for: replacing a Japanese bank account, paying a traditional landlord by domestic transfer, or every cash-only shop.
Watch: ATM withdrawal fees and limits, merchant card acceptance, and product eligibility that differs by your country of residence.

Yohji Ohtsubo
Why you can trust this guide
- Research basis: Research-based guide using Wise's published product model and current Japan payment norms
- Last checked: 2026-08-30
- Before you decide: Wise fees and eligibility change and vary by country — always confirm Wise's official live pricing before you move large amounts. General information, not financial advice.
If you earn in USD, EUR, or GBP but spend in yen, the quiet leak is usually FX, not ATM drama. Wise (formerly TransferWise) is the tool many nomads reach for to hold balances in multiple currencies, convert with transparent fees, and spend in Japan with a debit card — without a full local bank account for every situation. This guide covers where it works, what it costs, how it compares to a travel credit card, and where it does not replace local banking. For the wider budget, see cost of living in Japan for digital nomads; for arrival logistics, Digital Nomad Setup Japan.
\ Run a USD/EUR/GBP → JPY test conversion /
Fees and eligibility vary by country — confirm on Wise before large transfers.
Best choice by situation
| Your situation | Conclusion | Next step |
|---|---|---|
| Multi-currency income, months in Japan | Wise is a core rail | Open and verify now |
| You convert FX rarely | Compare total cost first | Run one test conversion |
| You need a Japanese bank account | Wise is not a substitute | Seek professional advice |
Pick the row that matches you, then complete the next step this week rather than parallel-comparing ten cards.
Japan's payment reality
Japan is high-tech and cash-stubborn at the same time. The infrastructure is excellent in cities, but paying rules are not uniform, and your wallet has to handle that.
- IC transport cards (Suica, PASMO, regional IC) are everywhere for trains and many small purchases — see Welcome Suica for digital nomads.
- Cards work often in cities, but cash still wins in small shops, some clinics, and rural days where terminals quietly disappear.
- Opening a Japanese bank account as a short-term visitor is often difficult. Wise is not a perfect substitute, but it covers a lot of card spending and some cash access via ATM.
The upshot: Wise is a strong layer in your wallet, not the whole wallet. Plan it next to IC and cash, not instead of them.
What Wise actually is
Wise offers a multi-currency account managed online, currency conversion between balances at a transparent rate with stated fees, a debit card (where available for your profile) accepted by Visa/Mastercard merchants, and — in some regions — local bank details useful when you receive client payments. The combination is what makes it interesting for nomads, not any single feature. It sits beside your home-country bank and reduces bad FX on day-to-day spending; treat it accordingly for tax and bookkeeping.
Wise card in Japan: what usually works
Retail and restaurants
Many urban merchants accept cards — especially chains, department stores, and larger restaurants — and contactless tap is common. A Wise card behaves like any other Visa or Mastercard at the terminal. In smaller independent shops, expect more variability.
Transport
IC cards remain the default for commuter rhythm; Wise does not replace Suica for every gate tap. Practical stack: IC for transit, Wise for dining/hotels/online, cash as backup. For tapping a Wise card through Apple Pay at gates, see Wise + Apple Pay at Japan train gates.
ATMs for yen cash
Convenience-store ATMs (Seven Bank, Lawson) and Japan Post Bank ATMs are frequently used by visitors. Compatibility, daily limits, and Wise's own withdrawal fees vary by card type and country — read Wise's help pages for Japan and your specific card before you build a heavy cash routine.
Online bookings
Hotels, domestic flights, and rail-pass purchases go smoother when your card profile matches your ID. Keep billing details consistent across Wise and the booking platform, especially if a 3-D Secure check appears at checkout.
Wise vs "travel credit cards"
Many credit cards advertise "no foreign transaction fee" but still bake margin into the exchange rate. Wise's pitch is transparent conversion fees — but compare apples to apples on a fixed amount:
- Total cost to get ¥10,000 spendable from your income currency.
- Speed of top-up and conversion (some rails settle in minutes, others overnight).
- Chargeback and purchase protection — credit cards sometimes win for high-ticket bookings.
Heuristic: Wise is often strongest when you move income between currencies frequently or want a yen balance to spend on demand. Premium credit cards can still win on perks and dispute support. Many nomads use both and split deliberately by purchase type.
A practical "Japan stack" for digital nomads
| Layer | Role |
|---|---|
| Income rail | Where clients pay you (Wise receive details if eligible, or your home bank) |
| Spending rail | Wise debit for card-accepting merchants; hold a yen balance or convert on demand |
| Transit rail | IC card (Suica or PASMO) — see the Welcome Suica guide |
| Cash pocket | Withdraw yen strategically; avoid empty-wallet Sundays in quiet towns |
| Connectivity | eSIM or pocket Wi-Fi so 2FA and Wise notifications work — compare options |
First week in Japan: a sensible payment order
- Day 0–1. IC top-up for transit and small buys. Do not optimize FX while jet-lagged; get sleep and data working first.
- Day 2–3. Use Wise where cards work cleanly — chains, hotels, online — and watch for declines. If a merchant fails, switch to cash without ego.
- Day 4 onward. Withdraw yen strategically where you see cash-only patterns, and track ATM fees as part of true cost. Cheap cash you bled out in fees is not cheap.
- Ongoing. Reconcile weekly in yen — mental accounting beats surprise statements at month end, especially when income arrives in another currency.
Mistakes that cost more than ATM fees
- Converting huge sums "just in case." Idle yen balances tie up money; convert closer to actual spend dates.
- Using Wise for every micro-purchase. Sometimes IC or cash is faster and cleaner in tiny shops with a queue behind you.
- Ignoring card-decline UX. Have Plan B cash before dinner with clients — do not learn about a fraud lock at the table.
- Mixing personal and client money. Bookkeeping pain later is expensive, even if separation feels tedious now.
Limitations and honest downsides
- Not accepted everywhere. Some merchants are cash-only; Wise will not fix that.
- ATM costs. Withdrawal fees and limits bite if you lean on cash heavily.
- Account eligibility. Products differ by residency and verification — check Wise for your country of registration.
- Support model. Disputes and chargebacks are not identical to major credit-card networks — read the terms before relying on the card for high-risk purchases.
- Regulatory limits. Wise is not a universal replacement for local tax or business banking. Consult professionals if you invoice Japanese clients or stay long enough to raise residency questions.
Receiving client income
If clients pay you in USD, EUR, or GBP, Wise can sometimes simplify receiving via local bank details in supported regions — eligibility varies widely by country and account type. A practical pattern: receive in your home currency → convert only what you need for near-term yen spending → keep a buffer in your home currency for tax reserves and emergencies. Your accountant sets the rules for your situation, not a blog.
Security: treat Wise like a bank-adjacent power tool
- Use strong 2FA and store backup codes offline. SIM-swap attacks are real; Japan is not magically safer for digital risk.
- Lock or freeze the card in-app when you are not actively spending. Habit beats panic.
- Compartmentalize email risk: password manager, unique password, and a recovery email kept off your daily inbox.
- Do not screenshot balances in public cafés — shoulder surfing happens, and screenshots leak from cloud backups.
Wise and Japan's Digital Nomad Visa
The digital nomad visa is about immigration status and insurance — not which card you carry. Wise helps you move money practically; it does not substitute MOFA requirements, the ¥10 million income proof, or private health coverage that meets the published wording. Confirm visa eligibility on official sources first, then design your money stack so Wise covers card spending and fast FX once you arrive.
Why this matters for your budget
If your monthly burn sits in a mid-range nomad budget, a bad FX habit acts like a small tax on everything — coffee to rent deposits. Optimizing FX is boring work that compounds across a six-month stay, and Wise is one of the easier wins to lock in early.
Wise card in Japan: FAQ
Does the Wise card work in Japan?
Yes, as a spend-and-FX layer. It works at most card-accepting merchants (chains, department stores, hotels, online) and via contactless tap, and it can withdraw yen at some ATMs. It does not replace an IC card for transit, cash for cash-only shops, or a Japanese bank account for domestic transfers.
Can Wise replace a Suica or IC card?
No. Suica is transit infrastructure; Wise is a spend rail. They sit on different layers — plan to use both. For tapping through Apple Pay, see [Wise + Apple Pay at Japan train gates](/workstyle-tips/wise-apple-pay-japan-train-transit/).
Does Wise work at Japanese convenience stores?
Often yes for card payments, especially in major chains. Still carry cash and an IC card as backup — edge cases happen, and a konbini at 11 p.m. is not where you want to debate payment methods.
What are Wise ATM fees in Japan?
You can withdraw yen at some convenience-store and Japan Post ATMs, but Wise's withdrawal fees, free allowances, and limits vary by card and country, and the ATM operator may add its own fee. Check Wise's current terms for your card, and treat ATM fees as part of your true cash cost.
Is Wise cheaper than my bank?
Sometimes. Compare total cost on a fixed amount, not headlines. Some home banks have surprisingly good FX once you count card rewards; others quietly take a sizeable spread you only see if you do the math.
Can I pay rent in Tokyo with Wise?
Sometimes. Monthly furnished providers and serviced apartments often accept cards, while traditional leases may require Japanese bank-transfer patterns Wise cannot match. Ask the landlord or platform before you sign. For neighborhoods, see [where to live in Tokyo](/workation-city-guide/tokyo-digital-nomad-where-to-live/).
How long does Wise verification and card shipping take?
It varies by country, ID type, and address checks. Treat several days to multiple weeks as a realistic window, and order before your flight if you want to land card-ready.
Do I need a Japanese phone number for Wise?
Generally no for using the app, but a working data line for 2FA and notifications matters — see [eSIM vs pocket Wi-Fi](/nomad-goods/esim-vs-pocket-wifi-japan/) for stable arrival options.
Your setup week: one action at a time
- Monday — pick your row
- Decide whether Wise is a core rail or an occasional FX tool for your income pattern.
- Tuesday — kill parallel tabs
- Run one real USD, EUR or GBP to JPY test conversion instead of reading ten card blogs.
- Wednesday — run the checklist
- Work through the Japan Setup Checklist 2026 so money, SIM and insurance protect week one.
- Thursday — validate connectivity
- Confirm a data line for 2FA before you rely on public Wi-Fi.
- Friday — do one thing
- Open the account, order the physical card, or complete verification.
Pre-arrival money checklist
Account and card
- Wise account opened and identity verification complete in your country of residence
- Physical card ordered with a realistic shipping window and an address that can sign for delivery
- One small test conversion completed so you learned the app flow before larger amounts
Access and safety
- ATM compatibility checked (Seven Bank / Lawson / Japan Post) plus current Wise withdrawal fees and limits
- Strong 2FA enabled, backup codes offline, recovery email separate from your daily inbox
- At least one credit card and a small cash reserve so you are never one decline away from a problem
- Personal vs client money separated; a monthly yen reconciliation routine planned
\ Order the card with shipping margin /
Fees and eligibility vary by country — confirm on Wise before large transfers.
Article summary
- Wise works well in Japan for card spending and converting foreign income to yen — but it is a layer beside IC and cash, not a Japanese bank account.
- Compare total cost on a fixed amount vs your bank and travel cards; watch ATM fees and merchant acceptance.
- Open the account and run a test conversion before you fly, and keep a credit card plus cash as backup.
Related articles
-

-
Wise + Apple Pay at Japan Train Gates: Does It Work? (2026)
Short answer: not reliably. A Wise card in Apple Pay is a contactless payment card, not an IC transi ...
続きを見る
-
-
Cost of Living in Japan for Digital Nomads: 2026 Monthly & 6-Month Budget
Quick answer: most solo digital nomads should budget roughly ¥180,000–¥400,000 per month in Japan — ...
続きを見る

-
-
Japan Digital Nomad Visa 2026: Requirements & How to Apply
The Japan Digital Nomad Visa is a six-month, non-renewable residence status for high-earning remote ...
続きを見る
-
-
Digital Nomad Setup Japan: 7-Day Arrival Checklist (2026)
Digital nomad setup in Japan works best in one order: confirm your legal stay and accommodation firs ...
続きを見る